
September 2026 Insights
Aspirations Wealth constantly monitors the investment markets and aims to keep our valued clients regularly informed and updated. We aim to help investors cut through all the media noise and hype and understand what is really driving investment markets and portfolio returns.
In this edition we cover:
The benefits of a bucket income retirement strategy
Bucket Income Planning in Retirement
Retirement can last 25 years or more. One of the most common questions we hear from clients approaching or already in retirement is: how do I generate reliable income while still giving my money the opportunity to last?
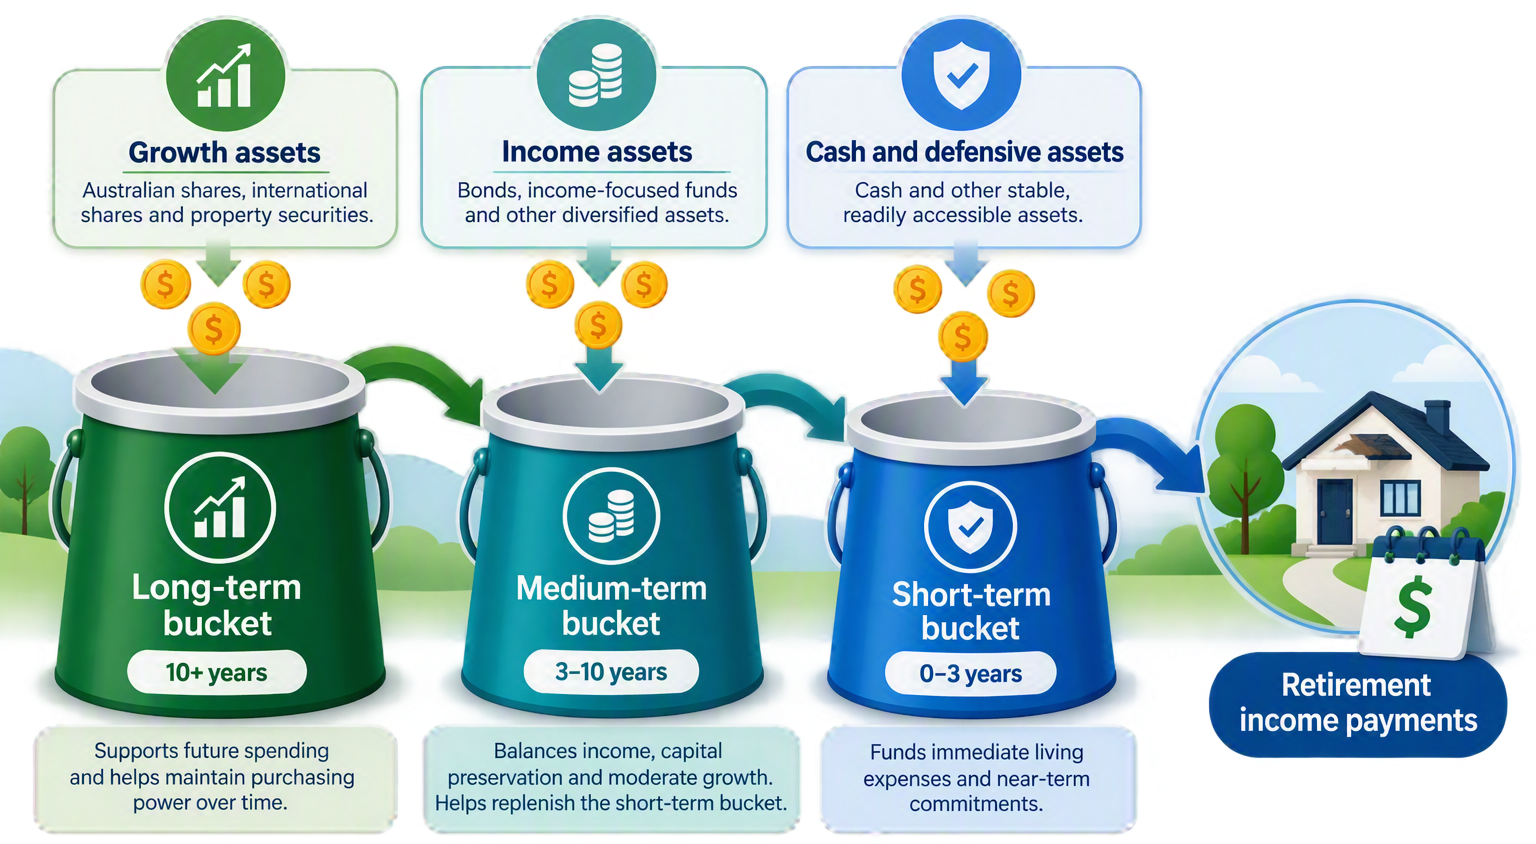
A bucket income strategy can help manage investment risk while providing a planned source of income throughout retirement. This strategy is a way of organising retirement savings into different pools, based on when the money is expected to be needed. Each bucket has a different purpose, separating short-term income needs from medium-term stability and long-term growth.
The Short-Term Bucket: 0-3 years
This bucket is designed to fund immediate living expenses and near-term commitments. It may include cash and other defensive assets that are more stable and readily accessible.
The key benefit is that if share markets fall, retirees are able to draw from their short-term bucket rather than selling growth assets at an unfavourable time.
The Medium-Term Bucket: 3-10 years
This bucket is designed to balance income, capital preservation and moderate growth. Over time, this bucket can help replenish the short-term bucket, while maintaining a more cautious profile than the long-term growth bucket.
The Long-Term Bucket: 10+ years
This bucket is designed to support future spending and help maintain purchasing power over time. It may include diversified exposure to growth assets such as Australian shares, international shares, and property securities.
While this part of the portfolio is expected to experience more short-term volatility, it plays an important role in helping retirement savings last throughout what could be a long retirement.
How the Buckets Work Together
Investment markets will always move through cycles. Interest rates, inflation, geopolitical events and economic data can all influence short-term returns. A bucket strategy is not about avoiding risk altogether. It is about taking the right type of risk in the right part of the portfolio, based on when the money is likely to be needed.
The short-term bucket helps meet regular income needs and provides flexibility.
The medium-term bucket can support stability and help replenish income reserves over time.
The long-term bucket provides exposure to growth assets that may help protect against inflation.
The overall strategy should be reviewed regularly as spending needs, market conditions, and personal circumstances change.
Why Retirees Use This Approach
Greater confidence during market volatility
Keeping short-term income separate can reduce the need to sell growth assets during market downturns.
Clearer cash flow planning
A dedicated purpose for each bucket makes it easier to understand where retirement income will come from.
Reduced financial stress
Having funds set aside for near-term spending can provide greater peace of mind during uncertain markets.
Long-term growth potential
Covering short-term needs separately allows growth investments more time to compound and recover from market fluctuations.
Flexibility as circumstances change
The strategy can be adjusted over time to reflect changes in spending needs, markets, and personal goals.
A Practical Example
Consider a retiree with $1 million in retirement savings who needs $50,000 each year to support their lifestyle. One possible structure could be:
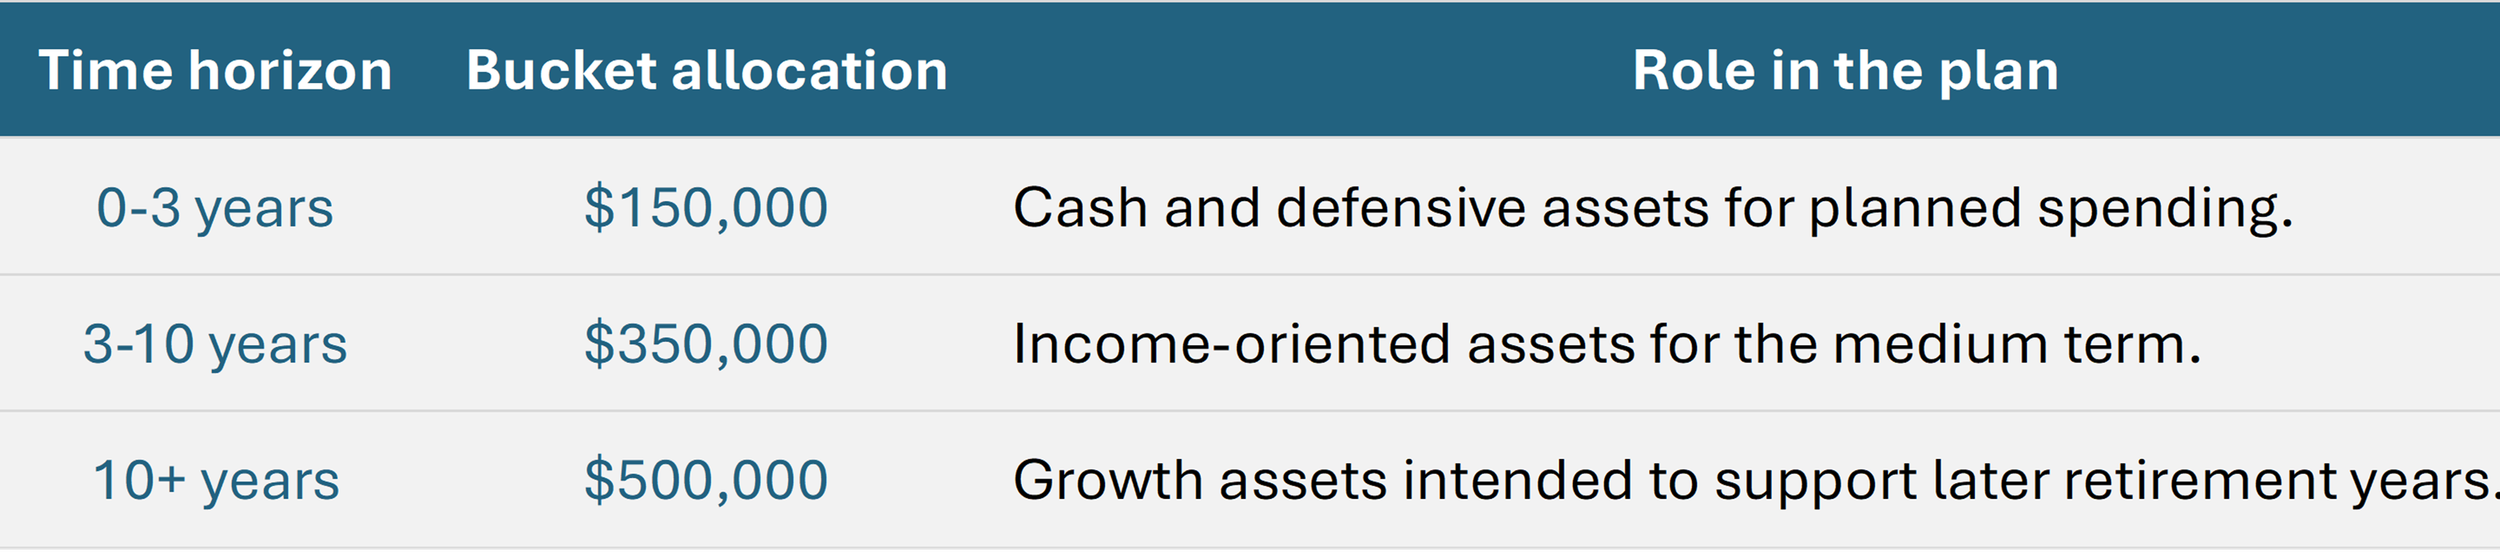
Important: This example is illustrative only. The appropriate structure will depend on individual spending needs, superannuation balances, tax positions, investment preferences, other assets, and estate planning objectives.
How We Can Help
At Aspirations Wealth Group, we believe retirement is about much more than reaching a certain age or achieving a specific superannuation balance. It is about having the confidence to enjoy life, knowing your financial future has been carefully and strategically planned.
Our advice process considers how your income needs, lifestyle goals, investment timeframe and risk profile work together. For many clients, a bucket income strategy can form part of a broader retirement plan designed to provide income, flexibility and long-term confidence.
Any advice contained in this insight/update is general advice only and does not take into consideration the reader's personal circumstances. To avoid making a decision not appropriate to you, the content should not be relied upon or act as a substitute for receiving financial advice suitable to your circumstances. When considering a financial product please consider the Product Disclosure Statement.
Aspirations Wealth Group is a Corporate Authorised Representative of Aspirations Private Wealth Pty Limited. ABN 57 622 182 076 – AFSL 503889.